W-4 Withholding Calculator
Estimate your recommended 2026 W-4 withholding per paycheck — avoid a surprise tax bill or leaving a big refund on the table all year.
What this calculator does
Estimates your recommended federal withholding per paycheck based on your salary, filing status, dependents, and pay frequency — the same core logic behind Form W-4's worksheets, using current 2026 IRS tax brackets.
Who this is for
Anyone starting a new job, getting a raise, having a baby, or who got an unexpectedly large tax bill or refund last year and wants to correct their withholding going forward.
How this calculator works
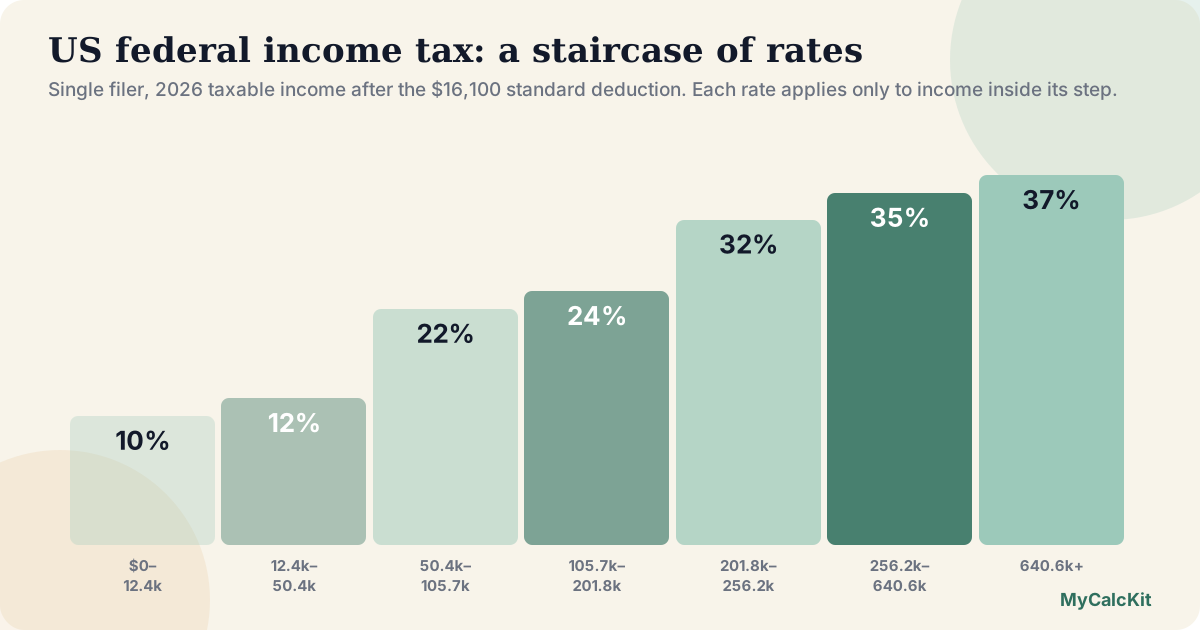
Estimated annual tax = 2026 IRS bracket tax on your salary after the standard deduction, minus Child Tax Credit ($2,200 per qualifying child) and the Credit for Other Dependents ($500 each). That net amount is divided across your pay periods, plus any extra withholding you specify (W-4 Step 4c).
Worked example
$75,000 salary, single filer, no dependents, biweekly pay: taxable income = $75,000 − $16,100 standard deduction = $58,900. Estimated annual tax ≈ $7,670 (per the 2026 brackets). Divided across 26 paychecks: $295/paycheck recommended federal withholding.
Same scenario but with 2 qualifying children: Child Tax Credit reduces the annual tax by 2 × $2,200 = $4,400, bringing estimated annual tax to $3,270. Divided across 26 paychecks: $126/paycheck — a real, immediate difference of $169 per paycheck from the dependents alone, illustrating why updating your W-4 after a life change matters.
Common W-4 Mistakes
- Two-job households not using Step 2. The single most common source of underpayment: both employers withhold as if the other spouse earns $0, producing a real balance due at filing. Checking Step 2(c) on both W-4s (for similarly-paying jobs) largely fixes this.
- Not updating your W-4 after a life change. A new baby, marriage, divorce, or side income all change your correct withholding — the form isn't "set once and forget."
- Claiming exempt without qualifying. Exempt status is only valid if you had zero tax liability last year AND expect zero this year — claiming it otherwise leads to a large bill and possible penalties.
- Assuming a big refund is "free money." A large refund means you gave the IRS an interest-free loan all year — adjusting withholding to be closer to your real liability puts that money in your paycheck instead.
Withholding per paycheck by salary
Federal withholding per paycheck for your filing status and pay frequency, with and without the credits you entered. Hover or tap to read; the marker follows your salary.
The gap between the lines is the Child Tax Credit and other-dependent credit, spread across the year. It narrows above $200,000 ($400,000 joint) as the credits phase out.
Where your paycheck goes
Run the calculator above to see the withholding vs. take-home split.
Sources & data
Figures checked on October 29, 2026.
Related calculators
Frequently Asked Questions
What's the difference between the old W-4 and the current one?
The W-4 was redesigned in 2020 to remove the old "allowances" system, replacing it with dollar-amount entries for dependents, other income, deductions, and extra withholding — a more direct, transparent approach.
What is Step 2(c) on the W-4 and when should I use it?
Step 2(c) is a checkbox for couples with two similarly-paying jobs. Checking it on both spouses' W-4s tells each employer to withhold using half the joint standard deduction, which corrects for the common under-withholding problem when both employers otherwise assume they're the only income source.
How much is the Child Tax Credit worth on my W-4?
$2,200 per qualifying child under 17, and $500 for other dependents, for the 2026 W-4. This reduces your estimated annual tax before it's divided across your paychecks, giving you the credit gradually rather than as a lump sum at filing.
What happens if I don't withhold enough?
You may owe an underpayment penalty if you withhold less than the IRS safe harbor: 90% of your current year's tax liability, or 100% of your prior year's liability (110% if your prior-year AGI exceeded $150,000).
Should I claim exempt on my W-4?
Only if both are true: you had no federal tax liability last year, and you expect none this year. Claiming exempt when you don't qualify can lead to a large tax bill and penalties at filing.