Income Tax Calculator
Estimate your 2026 US federal income tax using the current IRS brackets and standard deduction.
What this calculator does
Estimates your US federal income tax using current IRS brackets and the standard deduction for your filing status, showing how much of your income falls into each progressive bracket.
Who this is for
US taxpayers estimating their federal tax liability, anyone comparing a job offer, or people wanting to understand the difference between their marginal and effective tax rate.
How this calculator works
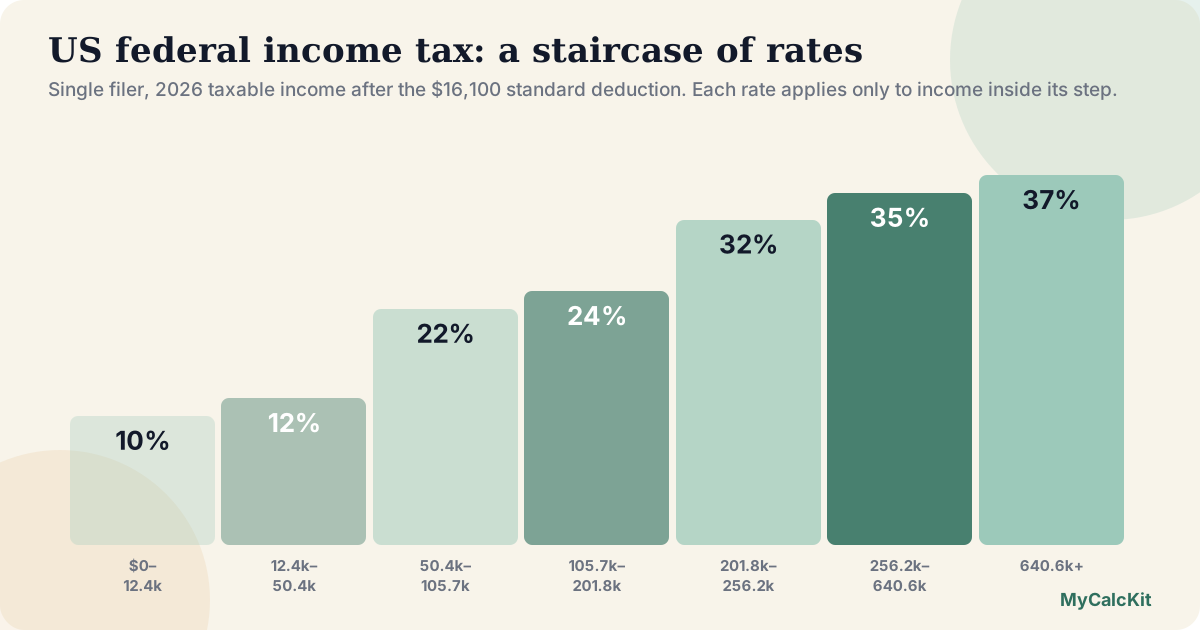
Uses the 2026 IRS federal tax brackets (Revenue Procedure 2025-32) and standard deduction. Your income is taxed progressively — each bracket rate only applies to the slice of income within that band, not your whole income.
| Rate | Single | Married filing jointly | Head of household |
|---|---|---|---|
| 10% | $0 – $12,400 | $0 – $24,800 | $0 – $17,700 |
| 12% | to $50,400 | to $100,800 | to $67,450 |
| 22% | to $105,700 | to $211,400 | to $105,700 |
| 24% | to $201,775 | to $403,550 | to $201,750 |
| 32% | to $256,225 | to $512,450 | to $256,200 |
| 35% | to $640,600 | to $768,700 | to $640,600 |
| 37% | over $640,600 | over $768,700 | over $640,600 |
2026 taxable income thresholds (Rev. Proc. 2025-32). Standard deduction: $16,100 single, $32,200 married filing jointly, $24,150 head of household.
Worked example
$75,000 gross income, single filer: taxable income = $75,000 − $16,100 standard deduction = $58,900. 10% × $12,400 = $1,240. 12% × ($50,400 − $12,400) = 12% × $38,000 = $4,560. 22% × ($58,900 − $50,400) = 22% × $8,500 = $1,870. Total federal tax = $1,240 + $4,560 + $1,870 = $7,670, an effective rate of about 10.2% on gross income — well below the 22% top marginal bracket.
A second example at $150,000 gross, married filing jointly: taxable income = $150,000 − $32,200 standard deduction = $117,800. Tax across the MFJ brackets totals $15,340, an effective rate of about 10.2% — notice this lands at almost the same effective rate as the single filer above at half the income, illustrating how much filing status and the doubled MFJ brackets shift the picture.
States With No Income Tax — What This Calculator Doesn't Show
This calculator estimates federal tax only, which is identical no matter which state you live in. But your total tax burden can swing enormously by state, and nine states currently charge zero personal income tax on wages: Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Washington, and Wyoming. Someone earning $100,000 moving from a high-tax state like California to a no-income-tax state can typically save somewhere in the $4,000-6,000/year range on state income tax alone.
"No income tax" isn't the same as "no taxes," though. These states raise revenue elsewhere: Texas and New Hampshire lean on high property taxes, Tennessee and Nevada on high sales taxes, and Washington, often listed alongside the others, taxes long-term capital gains above an inflation-indexed deduction (originally $250,000) at 7%, rising to 9.9% on gains over $1 million since 2025. Washington has also enacted a 9.9% tax on income above $1 million that is scheduled to start on January 1, 2028. Before assuming a move to a no-income-tax state is a straightforward win, it's worth running the full picture: property tax, sales tax, and cost of living can offset some or all of the income tax savings depending on your situation.
What this result means
Your effective tax rate will always be lower than your top marginal bracket, because only the income inside each bracket is taxed at that bracket's rate. Add state income tax (if your state has one) and FICA (7.65% for most employees) to get your true total tax burden — this calculator covers federal income tax only.
Effective vs marginal rate by income
Federal rate at every gross income for the filing status you selected. Hover or tap to read a value; the marker follows the income you entered.
After the 2026 standard deduction; effective rate is federal income tax divided by gross income. Excludes FICA and state tax.
Where your income goes
Run the calculator above to see the federal tax vs. take-home split.
Common mistakes
- Confusing marginal and effective rate. Being "in the 24% bracket" doesn't mean 24% of your whole income goes to tax — only the portion inside that bracket does.
- Forgetting state tax and FICA. This is federal income tax only. Your real total tax burden includes state tax (where applicable) plus 7.65% FICA for most W-2 employees.
- Not accounting for filing status correctly. Married filing jointly, single, and head of household all use different bracket thresholds — using the wrong one meaningfully skews the estimate.
- Forgetting the standard deduction before applying brackets. Tax brackets apply to taxable income (after the standard deduction), not gross income — skipping this step significantly overstates your tax.
- Assuming "no income tax" means "no taxes at all." States like Texas and Tennessee make up the difference with high property or sales taxes — the total tax burden can be closer to a high-income-tax state than the headline suggests.
- Assuming Washington has zero tax on all income types. Washington doesn't tax wages, but it does levy a 7% capital gains tax on gains above roughly $262,000 — a real exception within the "no income tax" list that catches people by surprise.
Sources & data
Figures checked on October 29, 2026.
- IRS Newsroom: IR-2025-103, 2026 inflation adjustments (Rev. Proc. 2025-32)
- IRS: Tax deductions for working Americans and seniors (tips, overtime, car loan interest, seniors)
- Bradford Tax Institute: 2026 federal tax rate schedules (all filing statuses)
- Baker Tilly: Washington millionaire tax (SB 6346)
Related calculators
Related reading
Frequently Asked Questions
Why is my effective tax rate lower than my tax bracket?
Your tax bracket only describes the rate on your last (highest) dollar of taxable income. Every dollar below that is taxed at the lower rates of the brackets beneath it, which is why your effective (average) rate across all your income is always lower than your top marginal bracket.
Does this include state income tax?
No, this is federal tax only. State income tax varies widely — some states (Texas, Florida, and others) have no state income tax at all, while others have their own progressive brackets.
What's the standard deduction for 2026?
$16,100 for single filers, $32,200 for married filing jointly, and $24,150 for head of household, per current IRS figures.
What's the difference between marginal and effective tax rate?
Your marginal rate is what you pay on your next dollar of income (your top bracket). Your effective rate is total tax divided by total income — always lower than your marginal rate.
Which US states have no income tax?
Nine states: Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Washington, and Wyoming. They typically make up the lost revenue through higher property or sales taxes, so total tax burden isn't always lower than a state with income tax.
Does Washington really have no income tax?
Washington doesn't tax wages or salaries, but it does levy a 7% capital gains tax on gains above roughly $262,000 — an exception worth knowing if you have significant investment income.